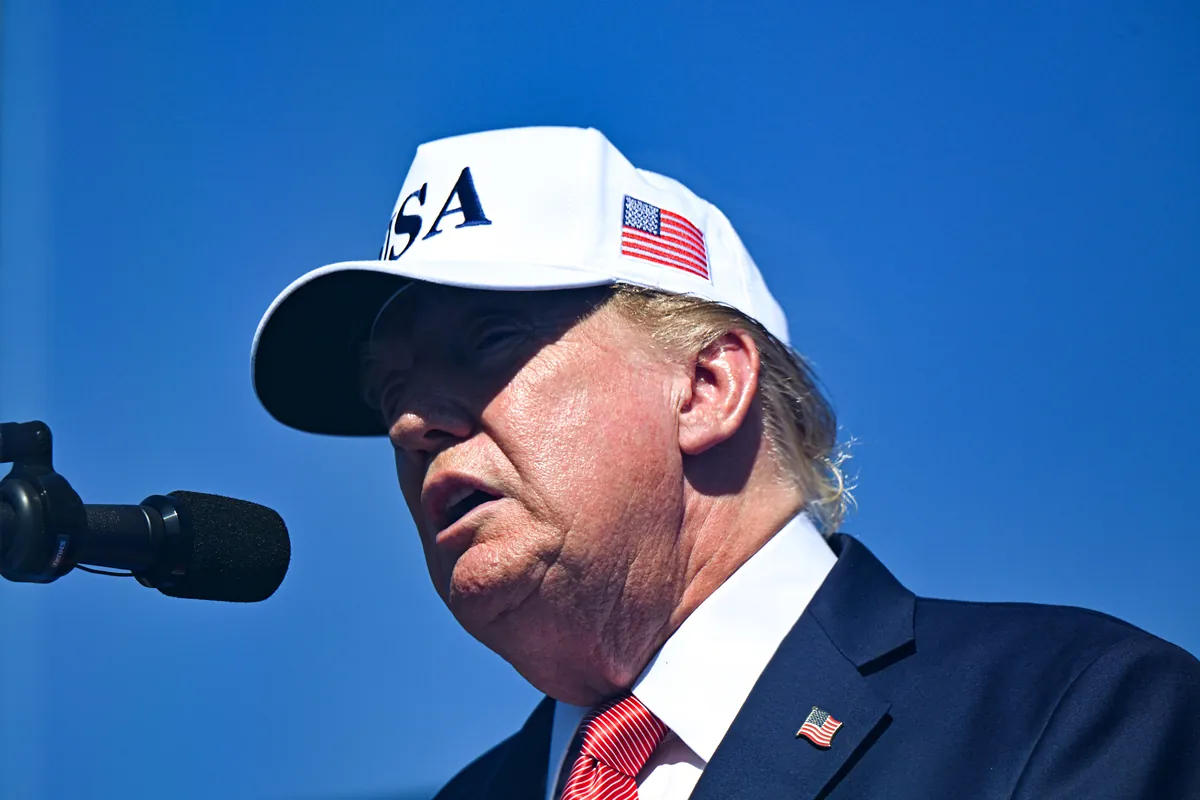
The United States and Canada escalated their trade war on September 8, 2026, as President Trump ordered Canadian products removed from U.S. federal procurement contracts hours after Canada imposed 50% retaliatory tariffs on American goods.
What happened
Canada began imposing tariffs of up to 50% on approximately CAD 27.6 billion (roughly USD 20 billion) worth of U.S. imports at midnight Eastern Time on September 8. The measure was itself a retaliation: the U.S. had already hit about USD 20 billion worth of Canadian goods with tariffs of up to 50% starting August 22, 2026.
Within hours, Trump posted on Truth Social ordering the U.S. General Services Administration (GSA) — the federal agency that manages government purchasing — to work with the U.S. Trade Representative (USTR) to strip Canadian products from the GSA Multiple Award Schedule (MAS). The MAS is a standing contract system that lets federal agencies buy pre-vetted goods and services from approved vendors; the program processes more than USD 50 billion in annual purchases. Trump framed the move as a response to what he called Canada’s trade fraud, citing dairy market restrictions and barriers against U.S. small businesses in Canadian government procurement.
Why Korea watches US-Canada trade fights closely
Exports account for roughly 40% of South Korea’s GDP, making Korea one of the most trade-exposed advanced economies in the world. When Washington escalates tariffs or procurement bans, the effects travel in two directions: directly, as Korean firms that supply components into North American supply chains face disrupted demand; and indirectly, as global risk sentiment shifts, putting pressure on the Korean won (KRW) and on Korea’s export-dependent equities.
Korea’s steel and auto sectors are especially sensitive. Canada is a major buyer of Korean-made vehicles, and both Canada and the U.S. are large consumers of Korean steel and petrochemicals. A prolonged US-Canada trade war tends to compress margins across the integrated North American supply chain, in which Korean manufacturers are deeply embedded as Tier 1 and Tier 2 suppliers.
What it means for you
Exporters and Korean manufacturers: Companies supplying components into the North American auto and steel supply chains — sectors that dominate the KOSPI (Korea Composite Stock Price Index, the main Korean equity benchmark) — face near-term demand uncertainty. Watch for earnings guidance revisions if the procurement ban widens to allied-nation goods.
Won/dollar watchers: Trade-war escalation typically triggers risk-off moves that weaken the KRW against the USD. A sharply weaker won raises import costs — especially for energy, nearly all of which Korea imports — which can feed through to utility bills and consumer prices. Check the current KRW/USD rate at the Bank of Korea (bok.or.kr).
Workers in exposed sectors: Korean auto assembly plants and steel mills that export to North America are the most directly exposed. No layoffs or production cuts have been announced; this is a policy escalation, not yet a factory-floor event.
Foreign residents and investors: This story has no immediate direct effect on rents, local wages, or Korean interest rates. The channel is indirect: if the trade war deepens and Korean growth slows, the Bank of Korea may adjust its policy rate — but that decision has not been made and would require additional data. Check the current policy rate at bok.or.kr.
Watch next
- GSA rule publication: The Trump order directs the GSA and USTR to take “all necessary steps” — the formal procurement rule change must be published in the Federal Register. No date has been set; decided by the GSA Administrator. Once published, it typically takes 30–60 days to take effect.
- Canada response: Ottawa has not yet announced a counter-measure to the procurement ban. Watch for a Canadian cabinet statement; date not yet set — decided by the Prime Minister’s Office.
- Korea’s monthly trade data: Statistics Korea and the Korea Customs Service release preliminary trade figures on the first working day of each month. The October 1 release will be the first data point capturing any September demand shock from this escalation.
Source: The Kyunghyang Shinmun (경향신문)
Was this useful?
What made the difference? Pick one.
What made the difference? Pick one.
Thanks. We read every answer.